WORKING WITH SCOTT STORICK, RFC® · BOCA RATON, FLORIDA
Life Insurance & Retirement Strategies Built Around You — Not a Product Quota.
Scott Storick has spent more than three decades in financial services, beginning at Guardian Life in 1992. Historical insurer announcements document his MDRT Top of the Table recognition. His approach starts with understanding your needs and comparing the options.
Start Here
What Are You Trying to Accomplish?
Deep Dives
Four Specialties. One Independent Advisor.
Scott Storick evaluates products across multiple carriers in each of these four areas — not to sell a brand, but to find the right fit for each client's specific situation and timeline.
No-Exam Life Insurance
Many applicants qualify for substantial coverage — term or permanent — without a blood draw, urine sample, or doctor visit. Simplified issue and accelerated underwriting decisions can arrive in hours to days. Health history doesn't automatically disqualify you; eligibility depends on the carrier and the contract.
- Same-week approval possible for qualifying applicants
- Term, whole life, and IUL options available without exam
- Compared across multiple carriers for rate and eligibility
Living Benefits Life Insurance
Certain life insurance policies include provisions — sometimes called "living benefit riders" — that allow eligible policyholders to access a portion of the death benefit after a qualifying health event: a critical illness such as a heart attack or cancer, a chronic illness affecting activities of daily living, or a terminal illness diagnosis. Not all policies include these provisions; eligibility and benefit amounts vary by contract.
- Critical illness: heart attack, stroke, cancer
- Chronic illness: qualifying daily-living limitations
- Terminal illness: typically 12–24-month prognosis
Indexed Universal Life (IUL)
Indexed universal life insurance is permanent coverage that credits interest based in part on a market index — such as the S&P 500 — while providing a floor (typically 0%) that prevents direct losses from index declines. IUL is commonly used for tax-advantaged retirement income, legacy planning, and supplemental wealth accumulation. Caps, participation rates, and policy charges affect actual performance — understanding the contract mechanics matters before any commitment.
- Tax-deferred cash value accumulation
- Floor limits index-linked losses to 0%
- Tax-free income potential via policy loans
Fixed Index Annuities
A fixed index annuity (FIA) is a contract with an insurance company that credits interest linked in part to a market index while shielding the contract value from direct losses when the index declines. FIAs are commonly used to generate guaranteed retirement income through an optional income rider, protect a portion of retirement savings from sequence-of-returns risk, and leave a defined legacy. Surrender periods, caps, and income rider costs are trade-offs every buyer should understand before signing.
- Principal protection from direct index losses
- Optional guaranteed lifetime income riders
- Not FDIC-insured — backed by issuing carrier's strength
The Process
Understand
Financial-needs analysis
Evaluate
Review goals, resources, concerns, time horizon
Explain
Plain English, no jargon
Decide
You make the informed decision
Review
Ongoing as circumstances change
Why Scott?
What Clients Actually Find When They Call
These aren't testimonials. They're representative situations from Scott's practice — the kinds of conversations that happen when someone calls with a real question and no agenda on the other end of the phone.
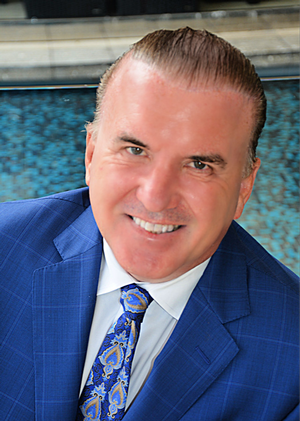
Scott Storick, RFC®
Scott has helped individuals and families make informed protection and retirement decisions since 1992. As an independent insurance professional with documented Top of the Table recognition, he starts with clear answers — the client-first approach behind the conversations below.
Health Concerns & Coverage
"I have health issues. I assumed I couldn't get coverage."
Many applicants who come with pre-existing conditions — diabetes, blood pressure, prior surgeries — find that no-exam carriers evaluate risk differently than traditional underwriting. Scott reviews their situation across multiple carriers to find which ones are willing to extend coverage at reasonable rates, without a medical exam. The answer isn't always yes. But it's rarely an automatic no either.
Representative situation — individual results vary by applicant, health profile, and carrier.
Retirement Income Planning
"Someone offered me an annuity. I wanted to understand it before signing."
Retirees regularly call after receiving a proposal from another advisor. Scott walks through the contract mechanics — surrender periods, participation rates, income rider costs, and what happens to the contract value if the income rider is exercised early. The goal isn't to replace the proposal. It's to make sure the person in front of him understands what they'd be agreeing to before they sign anything.
Representative situation — specific contract terms vary by product and carrier.
Living Benefits
"I didn't know life insurance could pay out before I died."
A significant number of Scott's clients come in asking about term life insurance and leave knowing that living benefit riders exist — provisions that may allow access to a portion of the death benefit after a qualifying critical, chronic, or terminal illness. Many weren't aware these provisions were available. Some already have a policy that includes them but have never read the rider. Scott explains how they work, what triggers them, and what the contract actually says.
Representative situation — living benefit eligibility and terms vary by contract.
Tax-Advantaged Accumulation
"My accountant mentioned IUL. I needed someone to explain it honestly."
IUL conversations at Scott's practice start with the mechanics — caps, participation rates, internal policy charges — not the projection. Many people come in having seen an illustration showing strong hypothetical returns. Scott explains what drives those numbers, where the assumptions live, and what a more conservative scenario looks like. The question isn't whether IUL is good or bad. It's whether it fits a specific person's situation, timeline, and tolerance for complexity.
Representative situation — IUL performance depends on contract terms, charges, and index behavior.
Independent
No carrier quotas. Products compared across multiple companies.
No Pitch
First call is a conversation. Scott answers his own phone.
30+ Years
In practice since 1992. Historically documented MDRT Top of the Table recognition.
Three Decades of Independent Service. Zero Career Interruptions.
Scott Storick began his career at Guardian Life Insurance in 1992, at age 27. Within his first six months in the industry, he qualified for the Million Dollar Round Table — a production benchmark most advisors take years to reach, and some never do.
Insurer-issued announcements document Scott’s MDRT® Top of the Table recognition, including 18 honors reported in 2017 and 21 reported in 2019. This production-based recognition is not a guarantee of investment performance or client results. See the About page for the original sources and current-status verification information.
His RFC® designation, issued by the International Association of Registered Financial Consultants, reflects his commitment to ongoing professional education. His SafeMoney Certified™ recognition reflects his specialization in principal-protection strategies and retirement income planning.
"I approach every client conversation the same way I'd want a financial professional to approach mine — with an honest explanation of how things work, including the parts that aren't in your favor."
Note: MDRT recognition reflects production volume; it does not guarantee results for any individual client.
Latest from SafeMoney.com
SafeMoneyLifeInsurance.com is owned and operated by Scott Storick, RFC®, and supported by SafeMoney.com as an educational initiative.
Frequently Asked Questions
Ready to Have a Conversation?
Scott answers his own phone. There is no assistant, no voicemail maze, no follow-up from a stranger. Schedule a conversation — no obligation, no pressure, no pitch until you've had your questions answered.
Prefer to talk now? Call Scott at (561) 984-6668.